Thursday, 21 April 2016

e-Skin Could Change the Way We Communicate with the World

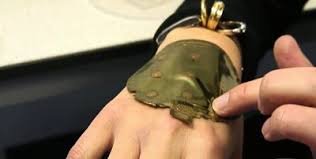
A new development reported by the University of Tokyo could help integrate electronics with the human skin in an unprecedented manner. The concept, being called the ‘e-skin’, essentially helps convert one’s skin into a digital screen. The researchers are trying to do so by using an ultrathin layer that will act as ‘electronic skin’ and display information about key health and fitness parameters. Athletes, for instance, can monitor their heart rate and blood oxygen levels using the device.

The team that has developed the e-skin demonstrated its use with an OLED display. With the integration of electronic devices with the body several new biomedical applications could now emerge. Researchers across the world are looking to go a step ahead of electronic wearables and embed electronics in the human body to enable better interaction between machines and humans.

However, that’s not an easy task considering that wearable electronics need to be extremely flexible, thin, and not be rejected by the body. Moreover, it is imperative that such electronics are attached to the body with minimal impact. 

Safe materials with millimeter-scale thickness have thus become the focus of researchers. In this regard, the key challenge faced by researchers has cropped up during the development of plastic substrates or glass that has thickness in the millimeter range but is still flexible enough and demonstrates stability when exposed to air.

What Can e-Skin Do?

The e-skin has been created using a protective film, which was developed by Professors Tomoyuki Yokota and Takao Someya, measures less than two micrometers in thickness and is ultraflexible. Besides the e-skin, the material can also be used in next-generation electronic devices and displays.

With the e-skin, it would be possible to display your emotions or your current stress levels via the flexible display that adheres to the body. The e-skin could also mean that people will have to carry fewer electronic devices and help improve the way we interact with the world. In short, it could create a whole new of communicating with people.

New Bone Grafts and Substitutes Aim to be Effective Treatment Methods for Chronic Wounds

For decades together, bone grafts and substitutes have been consistently used for bone structure restoration, regeneration, and pain relief. Autografts were conventionally used for bone grafting, where a patient’s own bone was utilized as a graft. Autologous bone grafts are considered to be the gold standard for bone transplant. However, the use of autologous bone grafts contains the risk of transfer of infection. Thus, allografts were introduced in the global market to overcome the limitations of and the disadvantages linked with autologous grafts. Bone grafts and substitutes are primarily used in numerous application areas including foot and ankle, dental, joint replacement, spinal fusion, and craniomaxillofacial procedures. 

As per the International Osteoporosis Foundation, the global incidence of fracture in men and women is expected to increase by 310% and 240% respectively by 2050. The growing incidence of fractures is expected to propel the global bone grafts & substitutes market in the years to come. The launch of new bone grafts and substitutes is expected to propel the global bone grafts and substitutes market. 

Recently, Cerapedics, based in Colorado, developed FDA-approved bone grafts for the cervical spine, which the company believes has the capacity to improve spinal fusion procedures. The company has introduced the i-Factor bone graft that aims at improving the fusion level that is supposed to be achieved during spinal fusions in the cervical spine. i-Factor is the second FDA-approved bone graft on the market after Medtronic’s In Fuse, which is approved for improving the lumbar spine.   

North America Bone Grafts and Substitutes Market to Expand at a 3.50% CAGR from 2015 to 2023 owing to Increased Focus on Patient Care

The global bone grafts and substitutes market is expected to expand from US$2.35 bn in 2014 to US$3.48 bn by 2023 exhibiting a 4.50% CAGR from 2015 to 2023 owing to factors such as rapid technological advancements and the penetration of synthetic bone grafts. The global bone grafts and substitutes market is segmented on the basis of type, geography, and application. Based on geography, the global bone grafts and substitutes market is divided into Europe, North America, Asia Pacific, Latin America, and Rest of the World. 

In 2014, North America dominated the global bone grafts and substitutes market followed by Europe. The North America bone grafts and substitutes market is predicted to expand at a 3.50% CAGR from 2015 to 2023. Factors such as continuous technological advancements, strict government regulations, and the rising focus on patient safety are expected to propel the North America bone grafts and substitutes market in the years to come. 

Allografts Segment to Drive Growth of Global Bone Grafts and Substitutes Market

Based on type, the global bone grafts and substitutes market is classified into allografts and bone graft substitutes. The allografts segment is anticipated to reach US$1.15 bn by 2023, registering a 3.90% CAGR from 2015 to 2023. The technological transition from autografts to allografts is predicted to propel the allografts segment in the next few years. Some of the application areas of bone grafts and substitutes are foot and ankle, spinal fusion, long bone, dental, joint reconstruction, and craniomaxillofacial. 


The DePuy Synthes Companies, Baxter International, Inc., Stryker Corporation, Zimmer Biomet Holdings, Inc., and Medtronic plc., are some of the leading players in the global bone grafts and substitutes market.

Wednesday, 20 April 2016

Global Aerospace and Defense Fuel Market Witnesses Development of Fuel Alternatives and Redesigning of Aircraft Wings

The global aerospace and defense fuel market has witnessed steady demand in recent years owing to the positive economic growth worldwide and the rising demand for aircraft from emerging economies such as India and China. While the emergence of low-cost airlines has boosted the demand for aviation fuel from the commercial sector, the growing need for surveillance aircraft and pilot training has created an opportunity for the growth of the market across the defense sector.

The growing awareness about carbon emissions and stringent government regulations about the same have stressed on the need for efficient carriers that promote fuel savings and reduce emissions. Even though carbon emissions from aircraft account for only 2% of the overall emissions, the aviation industry is taking initiatives to ensure carbon-neutral growth, which will augment the growth of the global aerospace and defense fuel market in the coming years.

New Alternatives to Aviation Fuel Emerge in Aerospace and Defense Sectors

The conventional petroleum-based liquid jet fuel is extensively used across the global aerospace and defense fuel market. However, the introduction of new alternatives is expected to decrease the dependency on petroleum-based liquid jet fuel.

> Renewable Jet Fuel: In an attempt to cut down on carbon dioxide emissions, United Airlines has started using aviation bio-fuel to run its commercial flights flying between Los Angeles and San Francisco. The airlines company expects to deploy 12,500 such flights running on bio-fuel to support energy diversification. The aviation bio-fuel is produced by AltAir Paramount with the help of Honeywell’s renewable jet fuel process technology, which converts non-edible animal fats and oils into renewable fuel. The green jet fuel is an ideal substitute for the petroleum-derived jet fuel currently used in flights.

> Synthetic Fuel: Commercial airlines and military aircraft usually run on synthetic fuels that are blends of Fischer-Tropsch (FT) fuels with traditional fuels. There are various petroleum-alternatives FT fuels such as coal-to-liquid (CTL) fuels, biomass-to-liquid (BTL) fuels, gas-to-liquid (GTL) fuels, and coal-and-biomass-to-liquid (CBTL) fuels.

Boeing Partners with NASA to Develop Super-thin Aircraft Wing

Some of the key players in the global aerospace and defense fuel market are Essar Oil Ltd., Indian Oil Corporation Ltd., Bharat Oman Refineries Ltd., Hindustan Petroleum Corporation Ltd., Reliance Industries Ltd., Kuwait Aviation Fuelling Company, Chennai Petroleum Corporation Limited, Royal Dutch Shell Plc, and Bahrain Petroleum Company. The volatility in aviation fuel prices is one of the primary factors affecting the key players and other commercial and defense aircraft manufacturers. While the key players are focusing on the development of alternative aviation fuels, aircraft manufacturers are working on redesigning aircraft wings to make aircraft lighter and thus decrease aircraft fuel bills. For example, Boeing has partnered with NASA to test low-drag, lightweight, and stiletto-shaped wings that would cut down aircraft fuel bills to half.

Such endeavors are expected to become common due to the rising awareness about the climatic effects of carbon emissions, propelling the global aerospace and defense fuel market.

Growth of Global Fire Alarm Equipment Market Attributed to Strict Implementation of Safety Guidelines

Considering the increased frequency of security issues and fire accidents, the fire alarm equipment market has achieved maturity over the years and at a global level. However, constant innovations – in technology as well as product – keeps this market dynamic and constantly expanding.

There are a variety of fire alarm systems and equipment available in the market today, such as smoke detectors, heat detectors, and flame detectors, which are used in public buildings, private buildings, commercial spaces, and industrial settings. Fire alarm equipment finds application in chemical factories, warehouses, theaters, airports, churches, drilling platforms, office buildings, waste treatment facilities, pumping stations, hotels, laboratories, large-scale garages, power plants, packaging facilities, apartments and houses, treatment facilities of chemical solvents, heat treatment, all kinds of ships, hospitals, museums, sewage plants, filling stations of inflammable fluids and gases, schools, cultural monuments, and petrochemical.

Surge in Building and Construction Activities Driving Demand for Fire Alarm Equipment

The fire alarm equipment market has been exhibiting strong growth and is forecast to witness steady growth in the coming years.

Listed below are some of the key factors driving the global fire alarm equipment market –

> The implementation of mandatory health safety guidelines is a major factor boosting the market for fire alarm equipment.

> The growing demand for fire alarm equipment from the construction industry is a prominent growth driver, given that new constructions and modern buildings for public facilities and housing are equipped with the latest fire detection systems.

> There are several stringent government regulations in place to ensure the safety of laborers working in various industries.

> Jurisdictional requirements by various countries – such as the Fire Protection Association in the US and the Building Code of Australia – have mandated the installation of fire detection devices such as fire and smoke alarms, a factor that greatly fuels the market for fire alarm equipment.

> The development of advanced technologies such as wireless sensory networks, human machine interface (HMI), smart building, and nanotechnology have greatly contributed toward the expansion of the fire alarm equipment.

> The growing awareness regarding fire protection and prevention among the general population has resulted in the greater need for fire alarm systems.

In contrast, the lack of effective control and proper compliance threatens to impede the growth of the global fire alarm equipment market.

Innovative Fire-Fighting Device Developed by World Patent Marketing

Manufacturer of patented products for entrepreneurs and inventors and an innovation incubator, World Patent Marketing announced the creation of the Firebox. This safety invention promises to improve the way homes and public buildings are protected against damages and losses caused by fire. Lack of accessibility to fire extinguishers and other fire-fighting equipment is one of the most common reasons for fire spreading in any establishment. The Firebox is a fire hose reel box, which is permanently connected to a water source. The unique feature of this invention is that the moment it detects a fire, the cover of the box is immediately opened to gain access to the hose. The Firebox is also fitted with an audio alarm and a light, both of which are turned on the moment a fire is detected.

Some of the leading players in the global fire alarm equipment market are Hochiki Corporation, TYCO, Secom, Protec Fire Detection, VT MAK, Mine Safety Appliances (MSA), Siemens, Johnson Controls, Bosch Security Systems, HALMA, United Technologies Corporation (UTC), London Security, Gentex Corporation, Mircom Group of Companies, and Honeywell.

Download Brochure: http://www.transparencymarketresearch.com/sample/sample.php?flag=B&rep_id=2596

Large Number of Untapped Shale Gas Reserves Lead to High Adoption of Hydraulic Fracturing Technology

Hydraulic fracturing is a technique that is used to extract natural gas and crude oil by injecting water along with propping agents and chemical additives. High temperature and pressure are used to create and open a network of fractures to enhance the permeability of the rocks. The adoption of hydraulic fracturing for the extraction of shale gas, tight gas shale oil, coal bed methane, and tight oil results in significant time and cost savings, which is one of the reasons for the increase in the adoption of this technique. According to a report published by Transparency Market Research, the hydraulic fracturing market, which stood at 21.34 MHHP in 2013 in terms of volume, is anticipated to expand at a modest CAGR of 5.30% from 2014 to 2022, to reach 33.97 MHHP by 2022.

Untapped Shale Gas Reserves in China Act as an Opportunity for Hydraulic Fracturing Technology

China’s shale gas deposits majorly lie in three giant basins: the Tarim Basin, the Ordos Basin, and the Sichuan Basin. The shale deposits in these reserves are embedded thousands of feet underground and the only means of getting to these reserves is through the process of hydraulic fracturing. The presence of shale gas reserves in China acts as a huge opportunity for the hydraulic fracturing market in the coming years, since China’s demand for oil and gas is among the highest in the world and increasing steadily.

Hydraulic Fracturing Leads to a Dramatic Rise in the Production of Oil and Gas in the U.S.

The shale revolution is a term used for the dramatic increase in the shale oil and gas production in the U.S. due to the adoption of hydraulic fracturing. The shale revolution has been a boon for the U.S. economy and has hugely benefitted the nation after the global recession in 2008, boosting the employment rate of the country. Political support has also helped in the growth of the oil and gas production, thanks to the elimination of restrictive policies and increasing support to the implementation of hydraulic fracturing. The growth of oil and gas production in the U.S. has counteracted the nation’s losses due to recession. It was the implementation of hydraulic fracturing methodology that led to this significant rise in the production of oil and gas.

Risk of Earthquakes due to Hydraulic Fracturing may Restrict its Adoption

Researchers in Canada have discovered that the injection of fracking fluids or stimulating fluids under high pressure, which is a part of the hydraulic fracturing process, creates fissures in impervious rocks and can ultimately cause earthquakes due to weakening of the bedrock. After the U.S., Canada ranks the highest in the world in terms of production of shale gas and oil. The country has faced frequent earthquakes in the Western Sedimentary Basin, which were attributed to improper waste water disposal and stress changes in hydrocarbon production. However, a recent study has revealed that the increasing earthquakes in the area are as a result of the excessive drilling. 

Tuesday, 19 April 2016

Viber follows in WhatsApp’s Footsteps, Introduces End-to-end Encryption

WhatsApp caused quite a stir in the messaging app industry when it announced that all chats would have end-to-end encryption. Besides putting governments on the guard and making some consumers wonder what the move means for them, the global messaging app has also caused many competitors to follow suit. Case in point: Viber. The messaging app, which boasts a user base of over 711 mn, also announced this week that all calls and messages on its platform would be encrypted end-to-end.

The wave of privacy features is expanding across the messaging apps ecosystem and no company now wants its consumers to think that it’s offering communications that are less private than the others.

The company, which has its roots in Israel, was acquired by Japanese company, Rakuten, in 2014. Viber said that its end-to-end encryption feature would be applicable to private chats, group chats, and calls. Going a step further, the company also added a feature that would allow users to ‘hide’ chats on their account.
  • These new services, the company has said, will be rolled out in the coming week. The rollout, which started on Tuesday, will happen across the world.
  • Initially, the new features will be available in four locations where the company’s R&D efforts are largely centered. These four locations are: Belarus, Thailand, Brazil, and Israel.
  • Viber’s new privacy features will be available across all Mac desktops, Android, PCs, and iOS provided the latest update of the app (6.0) has been installed. However, for the feature to be turned on, users will have to undergo a separate re-authentication process via a QR code.
  • All end-to-end encryption will feature varying levels of security, displayed through a color-coded lock, the company said.

Speaking of the reason behind introducing end-to-end encryption on its chats, the company’s COO, Michael Shmilov, told members of the press. With Viber introducing the feature just a few days after WhatsApp announced the same, the degree of competition that currently prevails in the private messenger apps landscape has become evident.

Sherwin-Williams’ Mega-acquisition of Valspar Could Have Major Repercussions in Coil Coatings Market

Metal coils are an important component in many undertakings, including construction and automotive design. Due to the crucial role coils play in various applications in the aforementioned industries, their longevity needs to be ensured. Coil coatings are used for just this purpose. Coil coatings, which can be of various types and are used according to the application, are primarily applied over metal coils to enhance their corrosion resistance. Corrosion of metal coils can endanger the structural integrity of the design, which illustrates the importance of coil coatings.

The rising demand from the construction and automotive industries around the world has propelled the global coil coatings market at a rapid pace in the last few years. The market was valued at more than US$4 bn in 2014 and is expected to rise to a valuation of US$6.3 bn in 2023. This projected expansion translates into a CAGR of 5.2% from 2015 to 2023.

Sherwin Williams’ Acquisition of Valspar Set to Shake Up the Competitive Landscape?

Competitively, the global coil coatings market is relatively consolidated, with the top four companies accounting for a 55% share in the global market in 2014. However, the competitive scales of the market may have been unsettled in a big way when, last month, Sherwin-Williams Co. announced its plans to acquire paints and coating giant The Valspar Corporation in a massive US$11.3-bn deal. The all-cash deal – the largest in Sherwin-Williams’ history – works out at US$113 per share. The global reach of Valspar Corporation is a crucial reason why the deal could work out immensely well for Sherwin-Williams and alter the global coil coatings market, as it could open up lucrative sales channels in the dynamic economies of Asia Pacific and the Middle East for Sherwin-Williams Co.

The construction and automotive industries in these two regions have experienced massive growth over the last decade. These two industries, being the two major application segments of the coil coatings market, will play a crucial role in the development of the coil coatings market in these two dynamic regions. Sherwin-Williams’ activities in these two industries in the coming years could go a long way in determining the global coil coatings market’s future.

Polyester Coatings to Dominate Global Coil Coatings Market

There are several types of coil coatings available in the global market, polyester, silicone modified polyester, plastisol, polyurethane, and polyvinylidene fluoride being the major ones. Of these, polyester coil coatings took up a dominant volume share of 60% in the global coil coatings market in 2014. Even though the polyester coil coatings segment is expected to remain dominant in the global coil coatings market, the polyvinylidene fluoride segment is expected to exhibit a faster growth rate in the aforementioned forecast period.

Construction Industry to Remain Dominant Application Segment of Coil Coatings Market

The construction industry accounted for two-thirds of the global coil coatings market in 2014. The rising nonresidential construction in Asia Pacific and the Middle East, with the latter benefitting massively from the 2022 FIFA World Cup being held in Qatar, will keep the share of the construction industry dominant in the coming years, though the application of coil coatings in appliances will increase at a higher rate.